In short: with indirect holdings, shares are not multiplied along the chain. Under Art. 2 TJPV, a person is a beneficial owner if they hold more than 50 % of an intermediate entity and that entity directly or indirectly holds at least 25 % of the company. Added to this are control in another way, acting in concert and fiduciary relationships. If nobody reaches the threshold, the most senior member of the management body is reported.
Contents: The basic rule in three sentences · Example 1: direct holding with different voting rights · Example 2: holding via a holding company · Example 3: two-level chain and the 50 % trap · Example 4: family company with a shareholders’ agreement · Example 5: a fiduciary holds the shares · Example 6: nobody reaches 25 % · The most common mistakes · How to document the chain
The basic rule in three sentences
First: a beneficial owner is a natural person who directly or indirectly holds at least 25 % of the capital or votes, or who controls the company in another way (Art. 4 TJPG). Second: indirectly means the person controls an intermediate entity with more than 50 %, and that entity holds at least 25 % of the company (Art. 2 TJPV); this applies at every level of the chain. Third: the size of the holding is reported in brackets (25 to 50 %, more than 50 to 75 %, more than 75 %) and, where two or more intermediate levels, a trust or a fiduciary relationship are involved, the whole chain with name, legal form, seat and UID is reported as well (Art. 13 and 15 TJPV).
The following examples are based on the collection of examples published by the Confederation for the transparency register. They show how the rules work in typical SME structures. The legal framework is summarised in the guide to the Swiss transparency register.
Example 1: direct holding with different voting rights
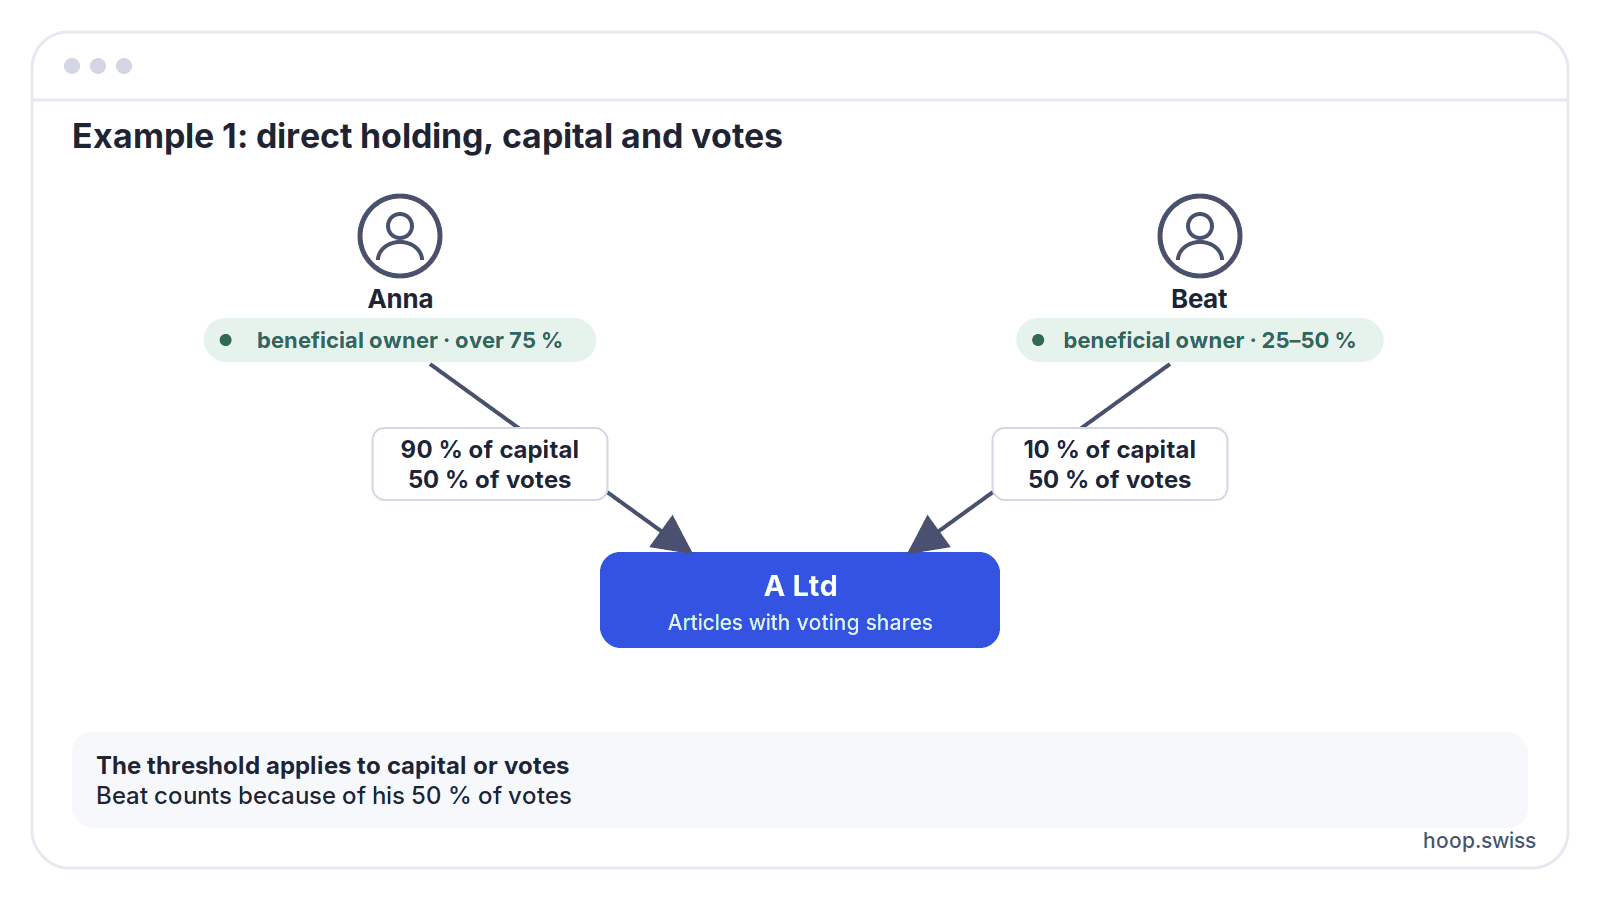
A Ltd has two shareholders. Anna holds 90 % of the capital but only 50 % of the votes, because the articles provide for voting shares. Beat holds 10 % of the capital and 50 % of the votes.
Result: both are beneficial owners. Anna because of her capital share (bracket over 75 %), Beat because of his votes (bracket 25 to 50 %), although his capital share is below 25 %. The threshold applies to capital or votes; voting shares, preferential votes or transfer restrictions therefore belong in the review.
Reported: Anna and Beat with the type of control “direct, alone, through a holding” and the respective bracket. No chain details needed.
Example 2: holding via a holding company
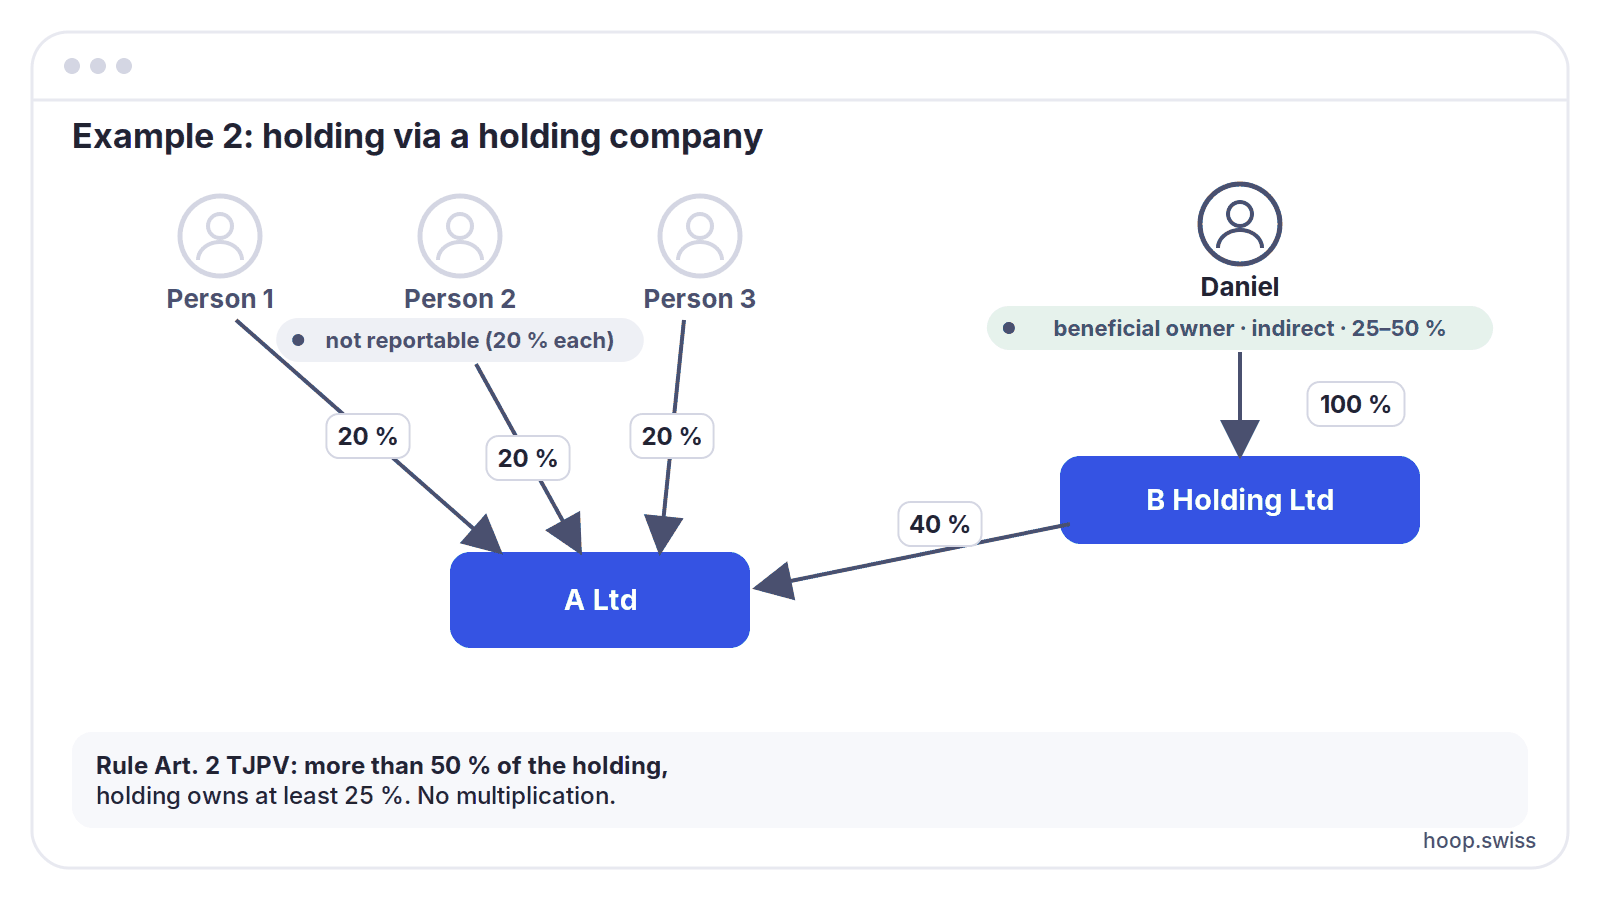
Three persons each hold 20 % of A Ltd. The remaining 40 % is held by B Holding Ltd. The sole shareholder of B Holding Ltd is Daniel.
Result: Daniel is an indirect beneficial owner: he holds more than 50 % of the holding company (100 %), and the holding company holds at least 25 % of A Ltd (40 %). The holding company’s stake is reported, i.e. the bracket 25 to 50 %, not a multiplied value. The three persons with 20 % each are not reportable.
Reported: Daniel, control “indirect, alone, through a holding”, bracket 25 to 50 %. Because there is only one intermediate level, the chain does not have to be reported with its UID.
Example 3: two-level chain and the 50 % trap
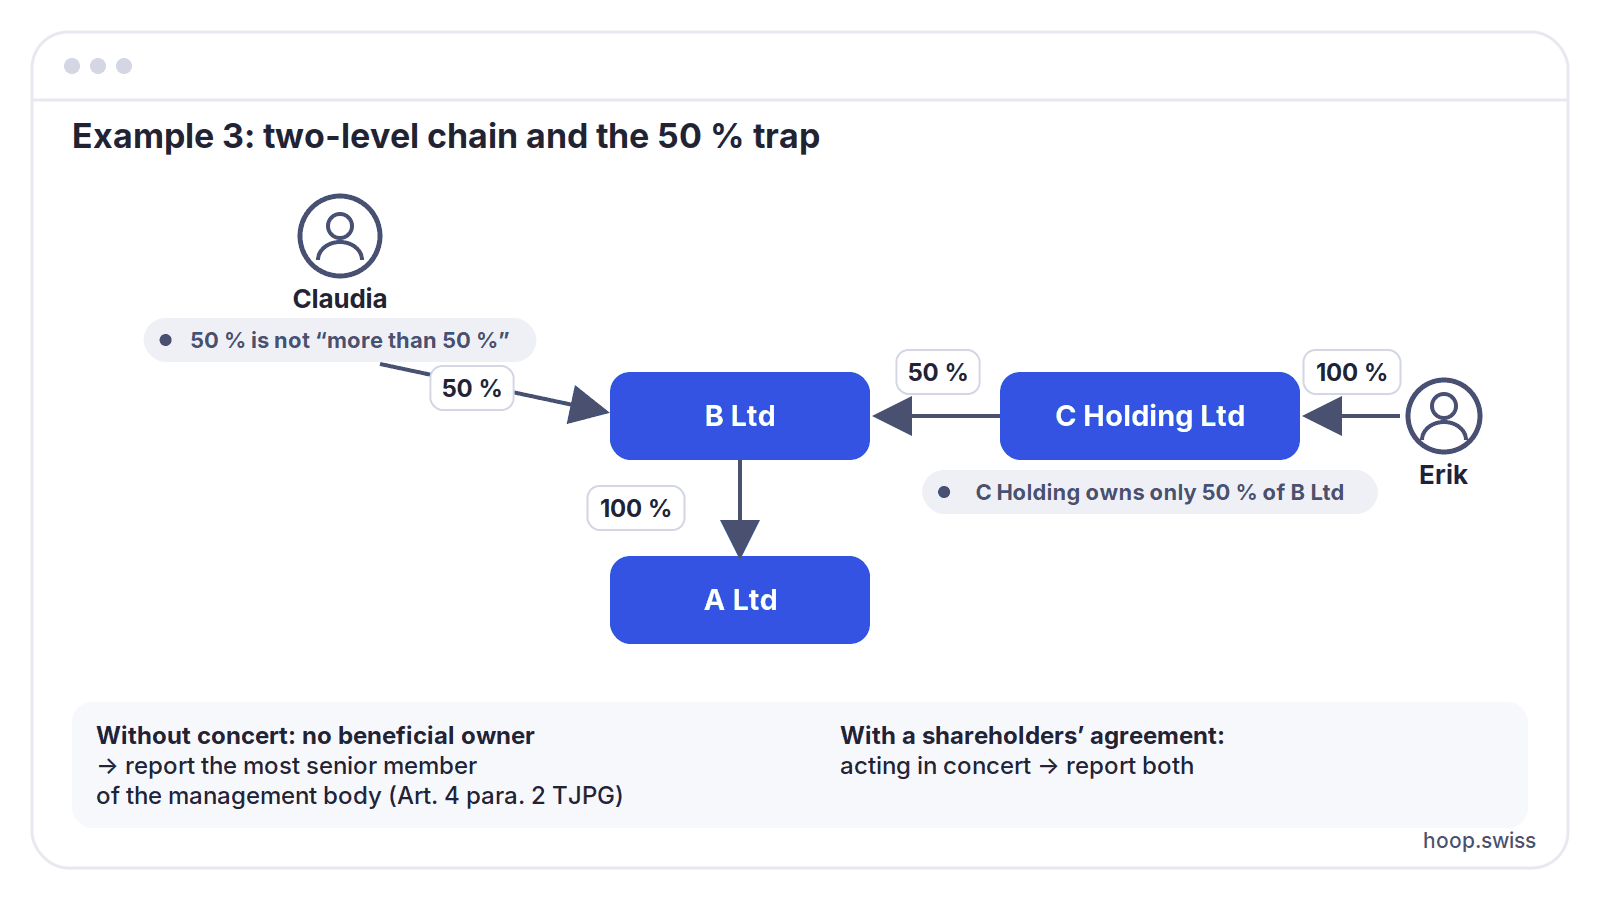
A Ltd is wholly owned by B Ltd. B Ltd is owned 50 % by Claudia and 50 % by C Holding Ltd, which is wholly owned by Erik.
Result: neither Claudia nor Erik is a beneficial owner through their holdings. Claudia holds exactly 50 % of B Ltd, i.e. not more than 50 %; Erik does control C Holding Ltd, but it also holds only 50 % of B Ltd. The common calculation “50 % of 100 % = 50 %” is misleading here: the ordinance requires a majority at each level, not a multiplied share.
However: if Claudia and Erik have coordinated their conduct, for example in a shareholders’ agreement, they are acting in concert (Art. 4 TJPV); then both are beneficial owners and the chain is reported. If one of them can appoint the majority of B Ltd’s board, there is control in another way (Art. 3 TJPV). Without concert and without other control, A Ltd reports the most senior member of its management body as a fallback.
Variant: if Claudia holds 60 % of B Ltd and C Holding Ltd 40 %, Claudia is an indirect beneficial owner in the bracket over 75 %, because B Ltd holds 100 % of A Ltd. Erik stays out: his C Holding Ltd holds only 40 % of B Ltd. For Claudia there is a single intermediate level, so the chain does not have to be reported with its UID; as soon as two or more levels lie between the person and the company, it is reported.
Example 4: family company with a shareholders’ agreement
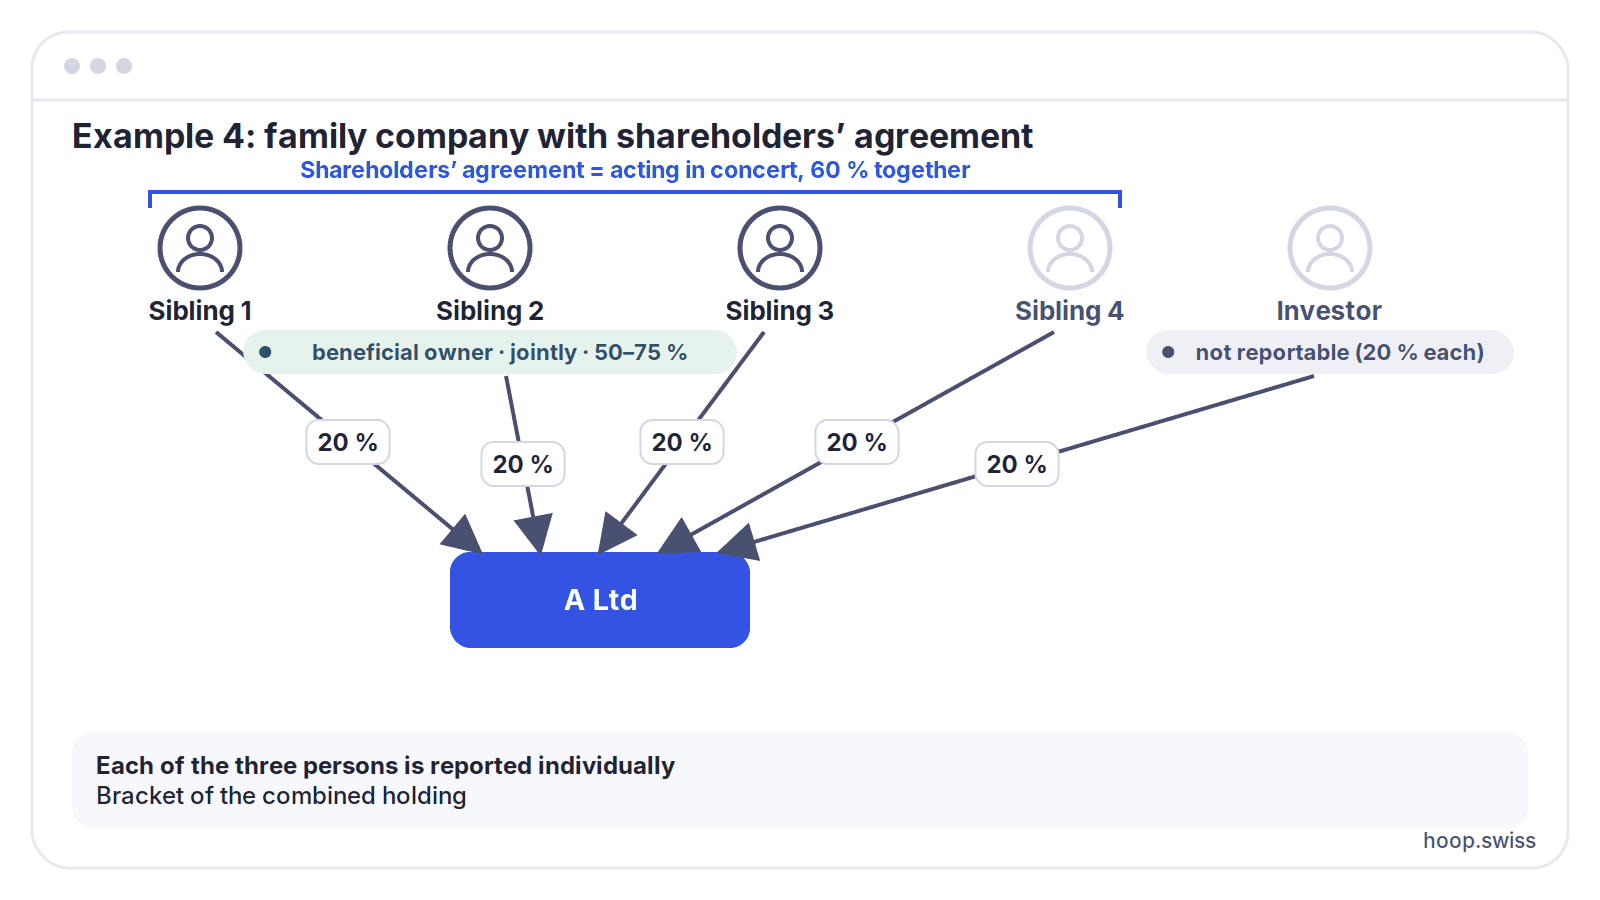
Four siblings each hold 20 % of A Ltd; the remaining 20 % belongs to an investor. Three of the siblings have concluded a shareholders’ agreement with voting commitments and pre-emption rights.
Result: the three siblings are acting in concert and together hold 60 %. Each of the three persons is a beneficial owner and is reported individually, with control “direct, jointly, through a holding” and the bracket of the combined holding (more than 50 to 75 %). The fourth sibling and the investor, with 20 % each and no agreement, are not reportable.
Typical triggers for acting in concert are shareholders’ agreements, family pools, voting agreements and pooling agreements between investors.
Example 5: a fiduciary holds the shares
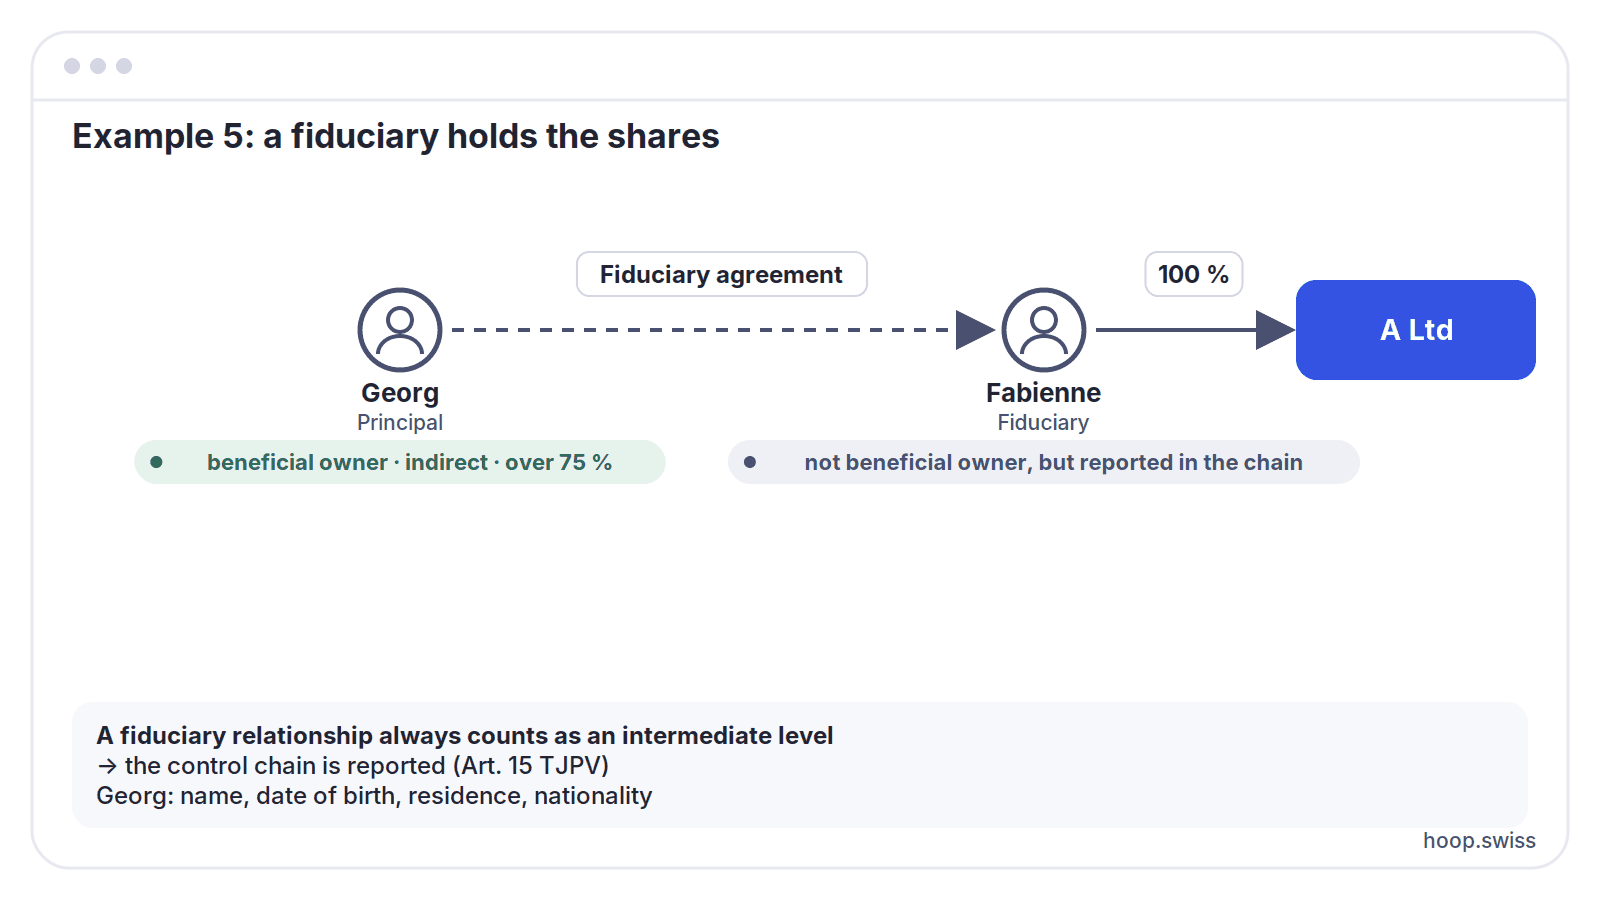
Fabienne holds 100 % of A Ltd, but as a fiduciary for Georg, who stays in the background.
Result: Georg, as principal, is the beneficial owner, control “indirect, alone”, bracket over 75 %. Fabienne is not a beneficial owner, but she is reported in the control chain with her role as fiduciary. A fiduciary relationship always counts as an intermediate level and triggers the chain details (Art. 15 TJPV).
The same applies if a company sits in between: if B Ltd holds 30 % of A Ltd and B Ltd is held by a fiduciary for Georg, Georg is an indirect beneficial owner (bracket 25 to 50 %); B Ltd with its UID and the fiduciary are reported.
Example 6: nobody reaches 25 %
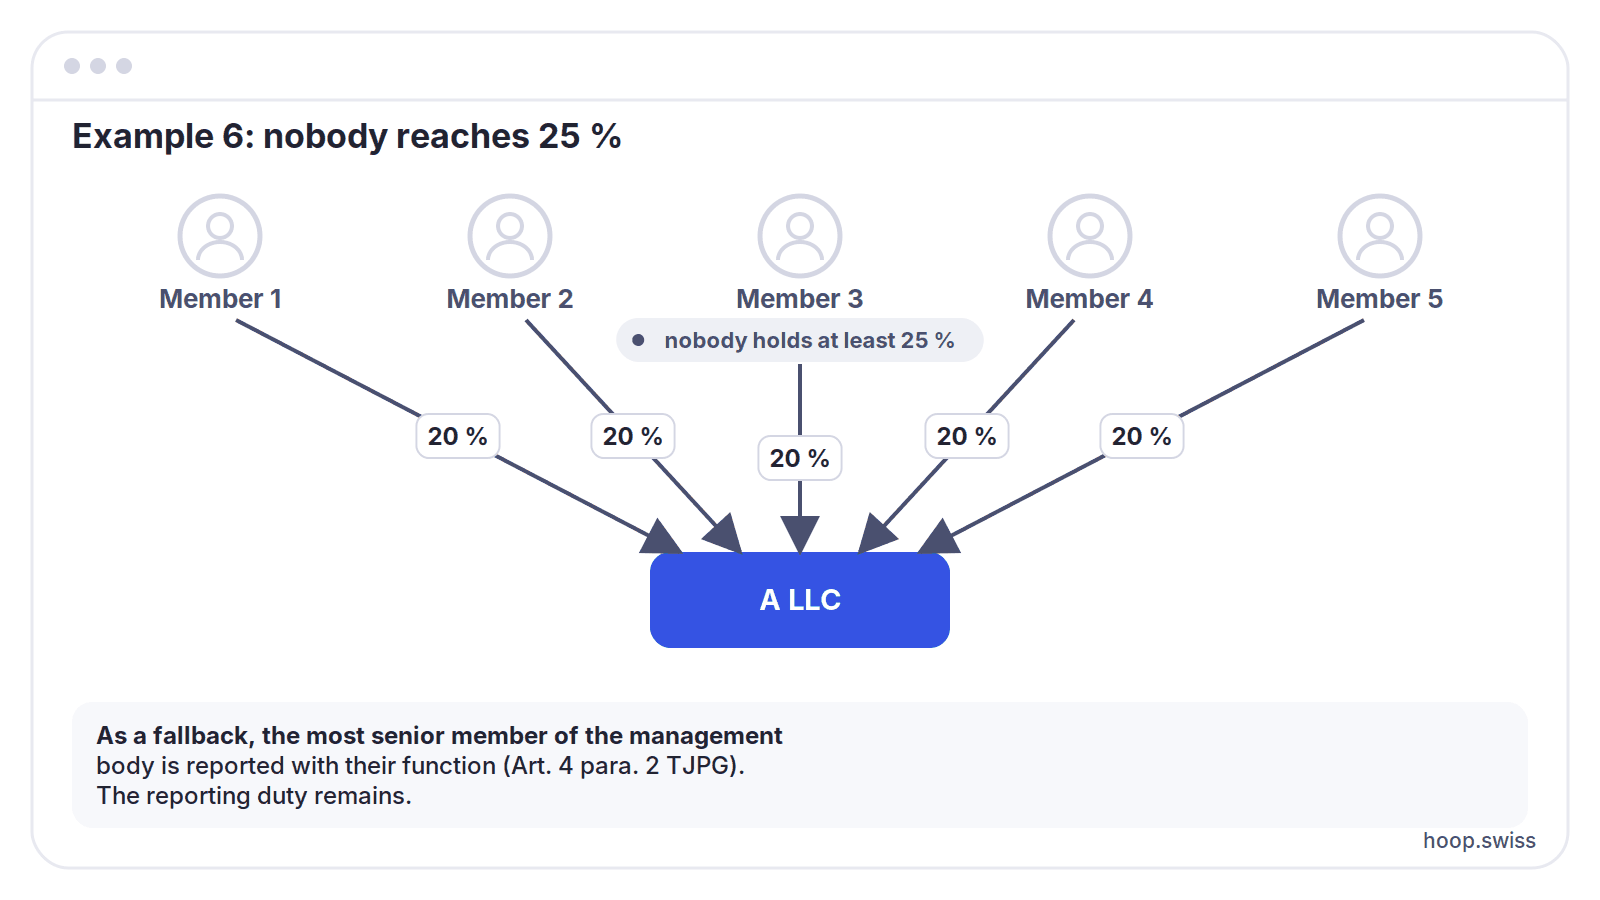
Five members each hold 20 % of A LLC. There is neither a shareholders’ agreement nor any special rights.
Result: nobody is a beneficial owner. The LLC reports the most senior member of the management body as a fallback, i.e. the chair of the management, with her function (Art. 4 para. 2 TJPG, Art. 20 TJPV). The same result arises with a holding company whose shares are split between three persons at 33 % each: at the second level the “more than 50 %” threshold applies, which none of the three reaches.
The most common mistakes
- Multiplying: 50 % of 60 % is not 30 %. What is checked is whether the person controls the intermediate entity with more than 50 % and whether that entity holds at least 25 %.
- Looking only at capital: voting shares, preferential votes and clauses in the articles can create a reporting duty even with a small capital share.
- Overlooking contracts: shareholders’ agreements, options, convertible loans and veto rights can mean control in another way or acting in concert.
- Forgetting fiduciaries and nominees: whoever holds the shares is not automatically the beneficial owner; the person behind them is reported, and the fiduciary appears in the chain.
- No documentation: the company must verify the information, evidence the chain and keep the documents for ten years (Art. 7 and 8 TJPG). A versioned share register with the ownership evidence is the simplest basis.
- Forgetting the fallback report: if there is no beneficial owner, the reporting duty remains; the most senior member of the management body is reported.
How to document the chain
- Draw the ownership structure as a diagram: persons, companies, trusts and fiduciary relationships with percentages for capital and votes.
- Check at each level: direct holding of at least 25 %, majority of more than 50 % in each intermediate entity, contracts and special rights.
- For each beneficial owner, obtain and evidence the information under Art. 10 TJPV: identity document or AHV number, residence, nationalities.
- Record the chain with name, legal form, seat and UID of the intermediate entities where two or more levels, a trust or a fiduciary relationship are involved.
- Enter the report on EasyGov and update every change within one month.
Frequently asked questions about control chains
How do I calculate an indirect holding?
Not by multiplication. Check at each level: does the person hold more than 50 % of the intermediate entity, and does the intermediate entity hold at least 25 % of the company? The intermediate entity’s holding in the company is reported in brackets.
When does the whole control chain have to be reported?
When at least two intermediate levels lie between the person and the company, when a trust is involved, or when there is a fiduciary relationship. Then the name, legal form, seat and UID of each intermediate entity are given.
What is control in another way?
The right or the actual ability to determine more than half of the board or management, to block key decisions or to force distributions, for example through contracts, options, conversion rights or provisions in the articles.
Are the shares of spouses or family members added together?
Only if the persons act in concert, for example through a shareholders’ agreement or a voting agreement, or if one person legally represents the other. Without such an arrangement, each person is assessed individually.
What about a foundation or an association in the chain?
Foundations and associations are not themselves subject to the reporting duty, but they can be an intermediate level. Then the special rules of Art. 7 or 8 TJPV apply, and the company identifies the persons who control the foundation or association.
What do I do if I cannot identify a person?
The company reports the available information, documents the steps taken and names the most senior member of the management body as contact person (Art. 9 para. 3 TJPG, Art. 21 TJPV). Shareholders who breach their reporting duty are also indicated.
Sources
- TJPG, SR 955.3, in particular Art. 4, 7–10, 13–15 (Fedlex, German)
- Ordinance TJPV, Art. 1–4, 10–15, 20–21 (Fedlex, German)
- Transparency register: collection of examples for determining beneficial owners (PDF, German)
- Transparency register: questions and answers (German)
Change log
- 19 October 2026: New version after the ordinance entered into force: examples follow the majority rule of Art. 2 TJPV instead of multiplication.
- 21 October 2026: legal references aligned across all language versions (Art. 7 and 8 TJPG, Art. 7 or 8 TJPV, Art. 21 TJPV).
Last updated: 2 November 2026
Next steps with Hoop
In Hoop’s digital share register you record holdings, voting rights and control chains with their evidence, identify the beneficial owners and prepare the report to the transparency register.
Digital share register · Register of beneficial owners with Hoop · What a register costs
For businesses that do it themselves: Share register for businesses
This blog article does not constitute legal advice, it is made available “as is” and makes no claim to completeness or accuracy. Hoop makes no warranty or liability as to its content. This is excluded to the extent permitted by law. Use is at your own risk. Legal advice is recommended if necessary.